When life strikes with unpredictable financial challenges, the luxury of waiting for a conventional personal loan approval is a choice most people don’t get. Whether you are staring blankly at an unexpected medical expense or trying to harness a deadline-driven business opportunity, the answer might already be stored safely in the hidden corners of your personal locker.
Maximizing the intrinsic value of your idle gold ornaments has now become one of the smartest, lucrative and fastest strategies to convert high value assets into active financial capital. As a matter of fact, renowned and reputable financial institutions like Indel Money have completely transformed this old school lending route into a smooth, seamless, customer centric experience marked by quick loan processing, high loan-to-value ratio and transparent rules and regulations.
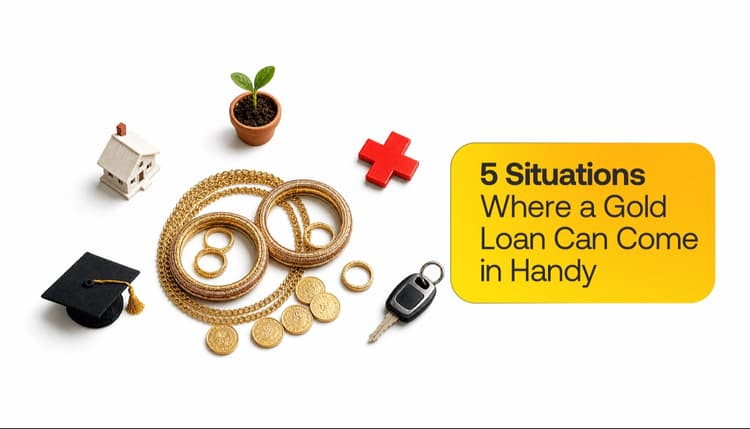
In this blog, Indel Money, one of the most popular gold loan companies in India sheds light on five common yet critical situations where leveraging a gold loan can safeguard your finances and keep your plans on track.
Medical emergencies never knock on your door before making an entrance, and hospital procedures often require immediate monetary liquidity before the actual treatment even begins. When insurance claims are faced with delays or your personal savings are tight. A gold loan becomes the source of emergency cashflow. Since lenders and financial institutions like Indel Money provide quick asset examination and rapid disbursal of funds with minimal paperwork, you can walk into a branch with your gold and walk out with liquid cash within minutes, thus getting rid of the immense strain and stress and that comes with pursuing formal credit approvals, allowing you to prioritize and focus on what matters the most to you - health, family, recovery.
For small business owners and micro-enterprises and self-employed individuals, cash flow can be obstructed out of nowhere. You might require immediate liquid cash to purchase machinery or raw materials at sudden discounts, fulfill a last minute bulk order or pay your staff their salaries during a tight phase. Conventional commercial loans often involve comprehensive credit evaluations, detailed credit vetting and administrative hindrances that can make you miss the next golden opportunity. But, capitalizing on gold loans in India allows your business to gain quick access to high value strategic liquidity without the need of cashing out primary assets or equity, ensuring daily operations run smoothly without any hassles.
Navigating the demands of multiple high interest debts such as credit card balances, personal loans or informal borrowings can pin you down in a compounding debt cycle. Centralizing these liabilities into one single structured gold loan can significantly minimize your overall interest burden. Since gold loans are secured assets, money lenders and non-banking financial institutions (NBFC) charge much lower interest rates when compared to unsecured credit cards. This transition simplifies and streamlines your debt repayment structure, brings down financial stress and anxiety and helps you clear your dues more faster without compromising on your long-term personal savings.
Tuition costs, academic deadlines and professional training fees often require accelerated settlements that may not be in sync with your monthly financial flow, waiting for a targeted education loan can often lead to missing a deadline or semester intake. In such urgent situations, a short term gold loan can close this gap with ease. It will allow you to pay for tuition or enrollment expenses almost immediately. Once your cash flow cycle stabilizes or you harness alternative funding sources, the availability of flexible repayment options and absence of heavy penalties make it even easier to settle your loan and reclaim the possession of your gold assets.
From unexpected home repairs like a broken ceiling fan to giving a fresh coat of paint to quick travel needs for personal purposes, temporary funding tightness can cause a dent on your monthly budget. Instead of liquidating high value long term assets, investments or trying your luck at mutual funds, which may give rise to exit loads to early termination fees, it is always better to pledge a small fraction of your gold as an alternative. Even though temporarily, it gives quick financial liquidity while making sure that your gold is safely locked up in a high security storage facility, waiting to bounce back into your hands once your cash flow cycle returns to normal.
Today, a Gold Loan is no longer perceived as a conventional fallback option when faced with financial uncertainties. It is a dynamic and flexible financial instrument designed to combat the economic challenges of the modern, fast-paced world. By joining hands with established and esteemed gold loan (NBFCs) in India like Indel Money, borrowers can avail a wide range of advantages such as secure asset (gold) management and storage, maximum value extraction, open-book costs structures, and discretionary payment parameters specially curated and customized to provide maximum customer comfort and peace of mind. Therefore, rather than allowing your gold holdings to remain dormant and unproductive, capitalizing its peak market valuation to attain financial resilience prepares you to withstand whatever challenge that lies ahead.
EMIs are the best way to make big loans feel easy. But this easy solution can become a headache if you don't have a clear financial plan.
Lakhs of people across India take gold loans every day for big purchases or emergency spending. The monthly installment feels manageable, but somewhere along the way, small mistakes turn this into a financial nightmare.
The good news is that these mistakes are entirely avoidable.
This is the most common one. A lender shows you a monthly installment that seems affordable, and you say yes.
But the EMI is just one number. What actually matters is the total amount you'll pay over the full tenure. Including the principal, interest, and processing fees.
A loan of ₹50,000 for two years with an interest rate of 18% costs more than a shorter loan period. When you choose to pay a lower EMI, you end up paying a lot more in the long run.
Always check the total amount that needs to be paid before opting for an EMI, as the monthly payments do not represent the total cost of the purchase.
If you think stretching your tenure to make the monthly EMI easy, you are wrong. In most cases, it isn't worth it.
As the tenure extends, you will have to pay more interest. Even at the same interest rate, a 3-year tenure costs significantly more than a 1-year tenure.
If you can, choose the shortest tenure you can manage based on your income.
One missed payment feels minor. The consequences aren't.
Missing an EMI directly hits your CIBIL credit score. When your credit score takes a hit, it becomes harder for you to secure future loans. You might also get burdened with higher interest rates because lenders may see you as a high-risk borrower.
On top of that, banks charge late payment penalties, and your outstanding balance can increase significantly.
Set up an auto-debit instruction from your bank account. Schedule it for the day after your salary credit. That one step removes the risk entirely.
This one is small but surprisingly common.
If your monthly paycheck hits your account after your EMI auto-debit, your account may have insufficient funds. As a result, your EMI payment will be considered missed, and your account may be charged a late payment penalty, bank charges, and a missed payment fee.
When you take a loan, choose an EMI date 3 to 5 days after your salary credit date. That buffer matters.
Many borrowers focus entirely on the interest rate and ignore everything else in the loan agreement.
But lenders can charge fees like processing fees, prepayment penalties, foreclosure charges, and bounce charges for failed auto-debits. These can add up to a meaningful amount over the loan tenure.
Before signing anything, ask for a complete breakdown of all charges. A regulated loan company in India will provide this upfront and clearly.
A single EMI is manageable. Three or four running simultaneously is where people run into trouble.
Financial planners generally recommend keeping your total EMI outgo below 40% of your monthly income. So if you earn ₹40,000 a month, your total EMIs across all loans should ideally stay under ₹16,000.
Many finance companies in India make it easy to split purchases into installments. That's convenient, but it adds up fast. A phone on EMI, a TV on EMI, and a personal loan EMI can quietly eat up most of your monthly income before you've paid rent or groceries.
Before taking a new loan, add up what you're already paying each month. Make sure there's room for the new EMI and your other expenses.
If you come into extra money, paying off part of your loan early is one of the smartest things you can do.
Prepayment reduces your outstanding principal. That means less interest is calculated on the remaining balance, and you can either lower your EMI or shorten the remaining tenure. Both outcomes save you money.
Some lenders charge a prepayment fee. Be sure to review this before you sign the loan agreement. There are several gold loan nbfc in India that charge little or no prepayment fee, and it is important to shop around before finalising the terms of your gold loan.
Missing a gold loan payment is stressful. But it doesn't mean you've lost your gold.
Gold loans in India are one of the easiest ways to get credit. You give your jewelry, get money promptly, and repay it over a set period.
Fortunately, the Reserve Bank of India has set rules to protect you at every step. The lender can't just take your pledged gold without proper notice and process.
In case you default on the gold loan, the lender will call you up and remind you to pay. Your lender will only put your gold up for auction after your account becomes a Non-Performing Asset (NPA) after 90 days of non-payment. Even so, they must give advance notice before any auction, and they'll return any surplus from the sale to you. |
One missed payment won’t trigger an auction.
Your lender will typically contact you by phone, SMS, or mail if you miss an EMI. A late payment fee and extra interest starting on the default date will be applied to late payments. Your credit score could also suffer if the lender reports the missed payment to a credit bureau.
Auction arises only if the account remains unpaid for over 90 days. If you don't repay the loan by then, it becomes a Non-Performing Asset (NPA).
So if you've missed one payment, the priority is simple: contact your lender immediately. Most trusted gold loan providers will work with you on a repayment plan before things escalate.
A lender can only auction pledged gold after following a regulated process defined by the RBI. The Reserve Bank of India has laid down guidelines that no auction can occur without proper notice to the borrower.
The process is usually as follows:
Once your account is classified as an NPA, the lender issues a formal demand notice.
The lender announces the auction in advance, stating the date, time, and outstanding amount.
This notice should give you a final chance to repay and recover your gold.
The minimum reserve price is 90% of the market price (if the auction is to be held).
Any auction proceeds that exceed the loan amount, interest, and charges will be returned to you within 7 working days.
Your gold remains your property until the auction is legally completed. Lenders cannot sell it quietly or without following this process.
The RBI has tightened gold loan regulations significantly to protect borrowers. These rules apply to all banks and gold loan NBFCs in India.
Key changes that affect borrowers include:
Loan-to-Value (LTV) ratios are now tiered. The lender can provide up to an 85% loan for gold loans of Rs 2.5 lakh and below. For loans ranging from Rs 2.5 lakh to Rs 5 lakh, the limit is 80%. For loans exceeding Rs 5 lakh, the limit is 75%.
To value gold, use the average price of 22-carat gold over the last 30 working days, as quoted by the India Bullion and Jewelers Association. This prevents arbitrary overvaluation.
Lenders should return the gold within 7 days of loan closure.
The valuation procedures, terms, and auction rules should be specified in detail in the contract in the borrower's language.
The rules are applicable to both bank loans and gold loans from NBFCs in India. As reported by Business Standard, the RBI introduced these tighter norms to bring more discipline and transparency to the sector.
There are more options than most borrowers realise.
The key is to act early! Let your lender know you may struggle to make your payment. RBI-regulated, trusted lenders can help people in temporary difficulty.
The following are some options that can be considered:
Partial payment: To prevent escalation and show good faith, partial payments can be made.
Loan restructuring: Trusted lenders may allow you to restructure the payment terms if your financial conditions are not favorable.
Interest-only payment: Interest-only payments can be made for some gold loans before starting to pay the principal.
Gold top-up/re-pledge: If the value of your gold has risen, you may be able to restructure the borrowing terms to allow longer grace periods.
The one element that always exacerbates the issue is waiting and hoping it will get better on its own. Missed payments compound and interest accumulates. And the window to act before an auction narrows.