

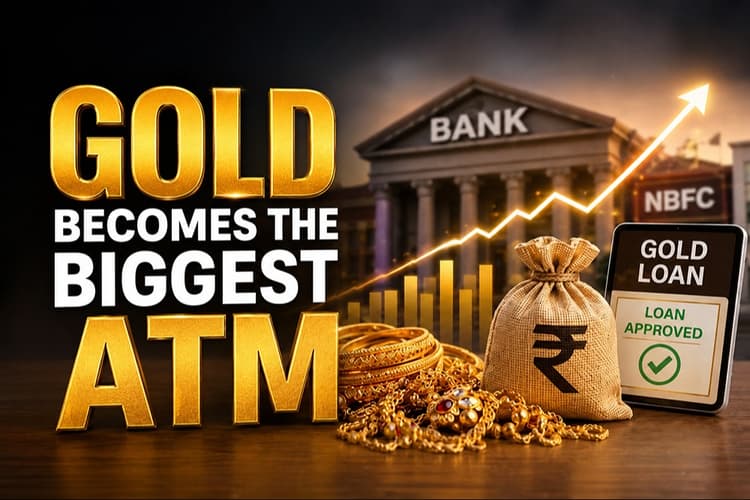
Loan against gold is a faster, simpler and convenient route for common man to meet financial emergency. Strikingly, gold loans are seeing accelerated growth in the domestic economy. RBI data on sectoral deployment of bank credit reveal that outstanding gold loans as on January 31, 2026, have grown past the Rs 4-lakh-crore mark, which records a remarkable growth of 128% year on year. Between January 2024 and January 2026, gold loans shot up by about Rs 3.1 lakh crore, signaling a four-fold increase in the loan portfolio.
In other words, gold loans have emerged as the second-largest retail credit product after housing loans. According to TransUnion CIBIL’s Gold Loan Landscape Report (published in April), gold loan balances have grown 3.8 times since March 2022, with their share in India’s retail credit portfolio rising from 5.9% to 11.1% by December 2025. This loan growth reflects rising borrower adoption, higher ticket sizes, broader lender participation, and a borrower profile that increasingly includes consumers and women with more extensive credit histories, the report added.
Multiple factors are driving this growth. Prominent among them is a steep hike in gold price. The prices have seen a massive surge, representing a growth of over 90% in the past 2-3 years. This phenomenal surge has prompted people to seek gold loan as a viable option to secure emergency funding. Moreover, a sharp jump in gold price will guarantee more money into the customer’s hands.
When gold price soars, it also offers ample scope for top-up loans. The lenders will be able to provide additional funding to the existing customers against the same amount of pledged gold. The cardinal principle that governs this business is the loan-to-value (LTV) ratio fixed by the RBI. It allows proportionate hike in loan amount when gold value increases, which ultimately results in the loan portfolio growth.
Second is digitalization. After the advent of new-age gold loan NBFCs, gold loans have become a faster and convenient route for people across rural as well as urban markets. Further, growing lender-fintech partnerships are effectively addressing legacy issues by launching cutting-edge solutions that are more compliance-driven and customer-friendly. It also alleviated the stigma attached to pledging gold, which is traditionally being considered as an auspicious cultural asset.
Third is RBI’s cap on unsecured retail lending by the regulated entities. As a result, availability of personal loans has become limited and expensive for sub-prime customers, and they were forced to look for alternatives such as gold loans and home loans for emergency funding needs.
Fourth is regulatory reforms. The banking regulator (RBI) has made the segment safer, secure and customer-friendly by enforcing clear protocols and guidelines on purity, valuation, storage, and auction of the collateral. The tiered LTV ratio, based on loan ticket size, is another remarkable step that ensures a level-playing field between all stakeholders.
Thus, organized gold loan market has grown spectacularly on high gold prices, robust GDP growth, expanding domestic consumption, higher credit demand, and RBI’s reforms. According to an ICRA study, the organised gold loan business was expected to reach Rs 15 lakh crore by March 2026 – a timeline much ahead of previously estimated– as banks and NBFCs were competitively strengthening their position in the market. The unabated gold rally is the prime reason for the lenders’ renewed vigour as it opens up one of the safest lending avenues for them. The market is now projected to reach Rs 18 lakh crore by the end of the current fiscal year (FY27).
What makes this segment resilient is its nature of asset-backed lending – an asset that is used by major central banks as strategic reserve. When a loan account turns ‘non-performing asset’ (NPA), it is easier for lenders to recover dues if timely auction takes place, as the collateral carries more intrinsic value than loan amount. So, the chances of loss-making are rare in the case of gold-backed lending.
A conservative estimate says that Indian households carry more than 25,000 tonne of gold, which has suddenly turned into a critical asset against the backdrop of unprecedented price surge. The current trend also reflects changing investor behaviour. Despite high prices, gold jewellery demand from India and China is seen persistent as more than 55% of global jewellery demand is coming from these countries. Investing in gold is seen as a hedge against inflation that helps people preserve their purchasing power over a longer period.
Gold has performed positively across market conditions, including lower as well as higher inflation. Thus, investors’ demand for gold, especially through ETFs, rose to the highest level in H1 2025 since 2020. Significant factors that drive the performance of the yellow metal are weakness in major currencies, low global interest rates, high inflation, economic slowdown, and demand-supply dynamics.
Historically, gold rallies in times of high inflation and economic uncertainties. However, there may be a fair chance of price correction after a specific period of rally. Historical data suggest that significant correction in gold prices is likely to occur after prolonged rallies, frequently appearing in a decadal cycle. But gold’s recent dips do not signal an end to bull run as geopolitical tensions are escalating day by day. Undoubtedly, the long-term trend for gold is bullish with each correctional phase setting the stage for future rallies and, ultimately, it is fuelling the gold loan market growth.

Buying a refrigerator, television, washing machine, smartphone, or air conditioner can be a significant expense. EMI options make these purchases easier to manage, but terms such as No-Cost EMI and Consumer Durable Loan can make the choice confusing.
The key difference is simple: No-Cost EMI describes the repayment structure, while a consumer durable loan is the financing product used to fund a purchase. In fact, a consumer durable loan can also be offered with a No-Cost EMI option.
Understanding this distinction can help you compare the actual cost, repayment terms, eligibility, and convenience before making a purchase.
A No-Cost EMI allows you to repay the financed purchase in equal instalments without an additional interest amount being charged to you under the stated scheme.
However, “no cost” does not necessarily mean there are no charges of any kind. Depending on the lender, product, or offer, processing or convenience fees and applicable taxes may still apply. Some schemes work because the manufacturer or merchant subsidises the interest component.
For example, suppose you purchase a ₹30,000 appliance under a six-month No-Cost EMI scheme. If the entire ₹30,000 is financed with no applicable additional charges, the repayment could be ₹5,000 per month for six months.
The exact amount should always be confirmed from the lender's repayment schedule before accepting the offer.
A consumer durable loan is a financing facility designed specifically for purchasing products such as household appliances, electronics, and other eligible durable goods.
Depending on the lender, the loan may cover products including:
Televisions
Refrigerators
Air conditioners
Washing machines
Mobile phones
Laptops
Kitchen appliances
Other eligible consumer products
Consumer durable loans can be offered through banks, NBFCs, and other eligible financial institutions. CIBIL notes that lenders may consider factors such as income and credit history when assessing applications.
For instance, Indel Money offers consumer durable loans for a range of products and currently lists benefits such as no down payment, no processing fee, No-Cost EMI options, flexible repayment modes, and up to 100% financing, subject to its applicable eligibility and product terms.
Factor | No-Cost EMI | Consumer Durable Loan |
Meaning | A repayment option where no additional interest is charged under the applicable scheme | A financing facility for purchasing eligible consumer durables |
Interest | Usually structured so the customer does not bear the interest under the No-Cost scheme | May be interest-free or interest-bearing depending on the product and lender |
Purpose | Makes a specific purchase payable through instalments | Provides finance for eligible durable purchases |
Availability | Usually available on selected products, merchants, cards, or loan offers | Offered by eligible lenders for approved products |
Fees | Processing/convenience fees may apply depending on the offer | Charges depend on the lender and specific loan |
Repayment | Usually fixed instalments over a selected tenure | Repayment depends on the sanctioned loan and agreed tenure |
The important point is that these are not always competing products. A consumer durable loan may itself come with a No-Cost EMI structure.

When you need funds quickly, a gold loan can provide access to money without selling your jewellery. The interest rate is usually the first figure borrowers compare, but it is not the whole story. Fees, repayment flexibility, tenure, valuation, and other terms can affect the real cost of borrowing.
If you are searching for the Lowest interest gold loan, compare the complete loan structure. Here are the factors that deserve attention before you pledge your gold.
Two lenders can offer similar rates while having different fees, repayment schedules, and product terms.
So the better question is not simply, “Who has the lowest rate?” Ask instead, “Which loan offers a reasonable overall cost and terms that fit my repayment capacity?”
Start with the interest rate, but understand exactly which rate applies to your chosen product. Check whether the quoted figure is annual or monthly, how interest is calculated, and whether any conditions apply.
A proper Gold loan interest rates comparison should use the rate applicable to your loan rather than a promotional figure alone.
Interest is not the only borrowing cost. Processing fees, taxes, valuation or documentation charges, and applicable late-payment or foreclosure charges can increase what you pay.
This matters particularly for smaller loans. Before accepting an offer, check the processing fee, applicable taxes, and all other charges associated with the product.
Loan-to-value, or LTV, determines how much you can borrow against the eligible value of your gold. The amount depends on purity, valuation, lender policy, and applicable regulatory requirements.
RBI rules govern lending against gold collateral and prescribe applicable LTV and valuation requirements for regulated entities. Therefore, the market value of your jewellery is not necessarily the amount you can borrow.
Borrow only what you need. A larger loan can also mean a larger repayment burden.
Gold jewellery is valued according to eligible gold content, not simply what you originally paid for it. Purity and net gold weight affect the eligible value.
Find out how purity is determined, how the total weight is calculated, and whether certain items such as stones or non-gold elements are subtracted from the final total, and which valuation process is applied.
In line with RBI instructions, regulated lenders have to use specified valuation procedures and provide information about the gold they use as security. A transparent method allows people to see what is behind the loan amount they received.
Repayment terms can matter as much as the interest rate. Gold-loan products may have different repayment structures, so understand when the principal and interest become payable.
Before signing, ask: “Exactly when and how do I have to repay this loan?”
The amount of time the loan stays unfulfilled is referred to as the tenure of the loan. The longer the tenure, the more time one has to organize repayments, although a longer tenure can lead to high overall interest charges.
The lesser the tenure, the shorter the loan period, although repayment might be faster. Choose a period that is suitable for your cash flow instead of automatically taking the longer duration.
Your financial situation can change. You may receive a bonus or another source of funds and want to close the loan early.
Flexible prepayment terms can be useful if you expect to repay ahead of schedule. Always check the specific product terms.
Late payments can incur more fees and some other implications if payments are not made.
Since the jewellery is being used as collateral, it is important that you know how the lender operates with delayed payments. It is better to ask them the questions related to notices, fees etc.
RBI has highlighted the need for regulated entities to follow proper practices when granting loans against gold jewellery.
A gold loan involves handing over jewellery, so security should be part of your comparison.
Check whether the lender has appropriate procedures for assaying, recording, storing, and returning pledged jewellery. RBI requirements for regulated lenders include measures relating to assaying, ownership checks, and safe custody.
Ask for clear documentation describing the jewellery pledged.
Finally, consider the lender itself. Clear and honest communication as well as access to customer service is essential when dealing with a financial obligation.
When assessing a loan company in India, pay attention to the reputation of the company, how easy it is to obtain that service, paperwork, repayment options, customer service, and the range of fees involved.
Having a lender with unclear terms may be more significant than having a different interest rate.

